 how-to
Medicare Advantage Enrollment Help: Buffalo Guide
Table of Contents
- Medicare Advantage Plan Basics
- Medicare Advantage Enrollment Deadlines and When to Act
- How to Switch Medicare Plans in 2026
- Working with an Independent Medicare Insurance Agent
- Local Enrollment Assistance Services and Resources
- Medicare Advantage for Dual-Eligible Individuals
- Pre-Enrollment Checklist and Common Mistakes to Avoid
- Conclusion
Last Updated: August 26, 2026
Medicare Advantage Plan Basics
Medicare Advantage is a federally approved alternative to Original Medicare that bundles hospital, medical, and prescription drug coverage into a single plan. Unlike Original Medicare, which is administered by the federal government, Medicare Advantage plans are offered by private insurance carriers approved by Medicare. These plans are also called Part C plans.
When you enroll in Medicare Advantage, you're choosing a specific insurance company's network and coverage rules instead of the traditional fee-for-service model. Most Medicare Advantage plans include prescription drug coverage (Part D) built in, which means you don't need to purchase a separate drug plan. Many plans also offer additional benefits that Original Medicare doesn't cover, such as dental, vision, and hearing services.
The trade-off is important to understand: while Medicare Advantage plans often have lower monthly premiums than Original Medicare with a Medigap supplement, they typically come with network restrictions. You'll need to use doctors and hospitals within your plan's network, or pay higher out-of-pocket costs. Prior authorization requirements are also common, meaning your plan may require approval before certain treatments or procedures.
Your Medicare Advantage enrollment help process begins with understanding these fundamentals. At Your Medicare Advantage Guy, we help seniors like you navigate these differences so you can choose a plan that aligns with your healthcare needs and budget.
Medicare Advantage Enrollment Deadlines and When to Act
Timing matters significantly when it comes to Medicare Advantage enrollment. Missing key deadlines can mean waiting an entire year before you can make changes to your coverage, with limited exceptions.
The Annual Enrollment Period (AEP) runs from October 15 through December 7 each year (cms.gov). This is the primary window when you can enroll in a new Medicare Advantage plan, switch between plans, or return to Original Medicare. Coverage changes take effect January 1 of the following year. If you miss this deadline, you'll be locked into your current plan until the next AEP arrives.
The Initial Enrollment Period (IEP) applies when you first become eligible for Medicare. This seven-month window begins three months before the month you turn 65, includes your birth month, and extends three months after (cms.gov). If you miss your IEP without a qualifying reason, you may face permanent late enrollment penalties.
Special circumstances create additional enrollment opportunities. If you experience a qualifying life event, such as losing employer coverage, moving out of your plan's service area, or becoming eligible for Medicaid, you may qualify for a Special Enrollment Period. These periods typically last 60 days from the qualifying event.
Understanding these Medicare Advantage enrollment deadlines is essential for avoiding costly gaps in coverage. Many people don't realize that once the December 7 deadline passes, you cannot change plans until the following October, regardless of your circumstances. This is where Medicare Advantage enrollment help makes a real difference in your decision-making timeline.
How to Switch Medicare Plans in 2026
Switching Medicare Advantage plans is possible, but the process requires careful planning and timing. Here's what you need to know about making a change in 2026.
Verify Your Eligibility
Before you can switch plans, confirm that you're eligible to make a change. If you're currently enrolled in a Medicare Advantage plan, you can switch during the Annual Enrollment Period (October 15 - December 7) without any restrictions. Your new coverage will begin January 1, 2027.
If you're approaching your Initial Enrollment Period because you're turning 65, you have a seven-month window to enroll. If you've already missed your IEP and have no qualifying life event, you may be unable to switch until the next Annual Enrollment Period arrives.
Check whether you've experienced a qualifying life event. Moving to a new state or county, losing employer-sponsored insurance, becoming eligible for Medicaid, or experiencing other major changes can trigger a Special Enrollment Period outside the normal annual window. Document the date of your qualifying event, as you'll need proof when you apply.
Gather Your Doctor and Pharmacy Information
Before comparing plans, compile a list of your current healthcare providers. Note your primary care doctor, any specialists you see regularly, your preferred hospital, and any facilities where you receive ongoing treatment. Call your providers' offices and ask whether they accept each plan you're considering. Network status can change, and a doctor who was in-network last year may not be this year.
Create a separate list of your current medications, including the drug name, dosage, and frequency. Visit Medicare.gov's plan finder tool and check each plan's formulary (drug coverage list) to confirm your medications are covered. Note whether your drugs require prior authorization or step therapy, where you must try a different medication first before the plan will cover your preferred drug.
If you use a specific pharmacy, verify that it's in-network for each plan. Some plans have preferred pharmacies with lower copayments, while others charge more at non-preferred locations. This detail often gets overlooked but can significantly affect your out-of-pocket costs.
Compare Plans Using Star Ratings
Medicare publishes Star Ratings for all Medicare Advantage plans, scoring them on a five-star scale across multiple categories: plan quality, member experience, and drug coverage (cms.gov). These ratings are updated annually and provide a meaningful way to compare plan performance beyond marketing materials.
A plan with four or five stars generally indicates strong performance in customer service, care coordination, and claims processing. Plans with lower ratings may have higher complaint rates or longer wait times for approvals. While Star Ratings aren't the only factor to consider, they offer objective data about how well a plan actually performs in practice.
Look beyond the overall star rating and examine specific categories. One plan might excel at preventive care but struggle with prescription drug coverage, while another performs well across the board. Your Medicare Advantage enrollment help should include a detailed review of how each plan you're considering is rated in the areas most important to your health.
Working with an Independent Medicare Insurance Agent
An independent Medicare insurance agent operates differently than agents who work for specific insurance carriers. Independent agents represent multiple plans and are not compensated more for steering you toward one carrier over another. This structure creates alignment between your interests and the agent's incentive to find you the right fit.
When you work with an independent agent, expect a consultation that focuses on your specific situation. The agent will ask about your current doctors, medications, and healthcare patterns. They'll explain the differences between plans in plain language, not insurance jargon. A good agent will also discuss trade-offs honestly, acknowledging that no single plan is perfect for everyone, and that your choice involves balancing premiums, deductibles, network access, and drug coverage.
Independent agents can also help you understand concepts that confuse many seniors. Prior authorization requirements, network adequacy, Star Ratings, and the difference between copayments and coinsurance become clearer when someone explains them in the context of your actual healthcare needs. They can also identify plans that offer supplemental benefits like dental or vision coverage if those services matter to you.
The best independent agents stay current on annual plan changes. Networks shift, formularies are updated, and Star Ratings change each year. An agent who reviews your situation annually, even if you decide to stay with your current plan, ensures you're not missing a better option that emerged during the year.
Local Enrollment Assistance Services and Resources
Free, unbiased Medicare Advantage enrollment help is available through multiple channels in your area. These services are funded by the government and designed to help seniors navigate the enrollment process without pressure to choose any particular plan.
The State Health Insurance Assistance Program (SHIP) provides free counseling to Medicare beneficiaries. Counselors are trained on Medicare rules, can explain your coverage options, and help you compare plans. SHIP services are available by phone, in person, and online. These counselors are not affiliated with insurance companies and have no financial incentive to recommend one plan over another.
Medicare.gov remains the official source for plan information, eligibility verification, and enrollment. The plan comparison tool lets you search by specific doctors and pharmacies to see which plans include them. You can also review detailed plan documents, formularies, and Star Ratings directly on the site. The Medicare helpline (1-800-MEDICARE) connects you with representatives who can answer enrollment questions and help you apply.
Local community organizations and senior centers often host Medicare education events during the Annual Enrollment Period. These sessions explain plan types, enrollment deadlines, and common mistakes. Attending one of these events gives you access to multiple resources and the chance to ask questions in a group setting.
Many local healthcare providers and hospital systems also offer enrollment assistance. Call your primary care doctor's office and ask whether they have Medicare specialists who can help explain how different plans affect your access to their services.
Medicare Advantage for Dual-Eligible Individuals
Dual-eligible individuals qualify for both Medicare and Medicaid, typically because their income and assets fall below certain thresholds. This population faces unique Medicare Advantage enrollment considerations that differ from standard Medicare beneficiaries.
Special Needs Plans (SNPs) are Medicare Advantage plans designed specifically for dual-eligible individuals. These plans coordinate benefits between Medicare and Medicaid, simplifying your coverage. SNPs are restricted to people who meet the dual-eligible definition, so you cannot enroll unless you qualify.
Medicaid coverage varies by state and can affect which Medicare Advantage plans work best for you. Some states have programs that pay your Medicare premiums and cost-sharing, reducing your out-of-pocket expenses. Understanding how your state's Medicaid program interacts with your Medicare Advantage plan is essential for managing your total healthcare costs.
Dual-eligible individuals should work with a counselor who understands both Medicare and Medicaid rules. Standard Medicare counseling may not address the full complexity of coordinating two government programs. SHIP counselors are trained on dual-eligible issues and can explain how different plans affect your Medicaid benefits.
Pre-Enrollment Checklist and Common Mistakes to Avoid
Taking time to prepare before the Annual Enrollment Period begins prevents costly mistakes and ensures you choose a plan that truly fits your needs.
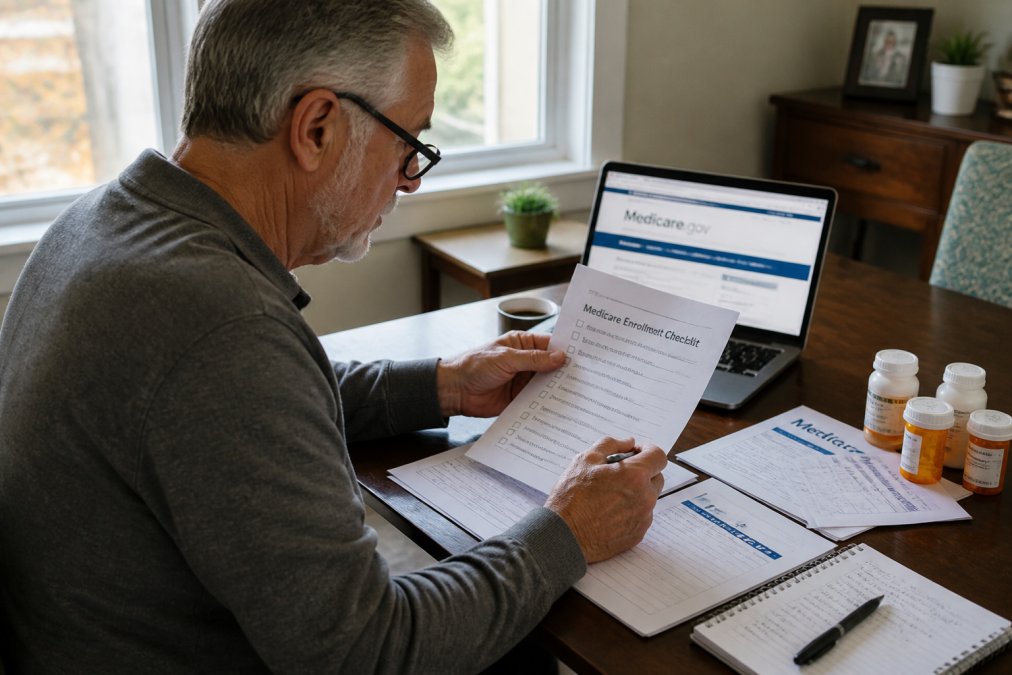
Pre-Enrollment Checklist:
- Confirm your current doctors accept Medicare and are in-network for plans you're considering
- List all current medications and verify they're covered on each plan's formulary
- Check whether your preferred pharmacy is in-network and note any copayment differences
- Review Star Ratings for plans you're seriously considering
- Understand the plan's deductible, copayments, and out-of-pocket maximum
- Confirm your hospital is in-network, especially if you have ongoing treatment
- Review supplemental benefits (dental, vision, hearing) offered by each plan
- Check whether your specialist doctors are accepting new patients and in-network
- Verify the plan's prior authorization requirements for procedures you use
- Document your qualifying life event if you're switching outside the Annual Enrollment Period
Common Mistakes to Avoid:
A frequent error is choosing a plan based solely on the monthly premium. A plan with a $0 premium but a $500 deductible and 40% coinsurance can cost far more annually than a plan with a $50 premium and reasonable cost-sharing. Calculate your estimated annual costs based on your actual healthcare usage, not just the advertised premium.
Another common mistake is assuming your doctor is in-network without verification. Networks change annually, and a doctor who accepted your plan last year may have left the network. Call the doctor's office directly and confirm their network status for the specific plan you're considering. Email confirmations are even better than phone calls, as they create a paper trail if billing disputes arise later.
Many seniors overlook the formulary when choosing a plan. A plan might seem perfect until you discover your blood pressure medication requires prior authorization or isn't covered at all. Review the formulary for every medication you take, not just your primary drugs. Check whether generic versions are covered if your doctor prescribes brand-name drugs.
Waiting until December to make a decision is risky. If you discover problems with your chosen plan after enrollment closes, you're stuck until the next Annual Enrollment Period. Starting your research in September gives you time to ask questions, verify network status, and make a confident choice.
Choosing the right Medicare Advantage plan doesn't have to be overwhelming. The combination of careful preparation, understanding your enrollment deadlines, and getting guidance from someone who understands your local healthcare landscape makes the process manageable.
Your Medicare Advantage enrollment help should come from someone who takes time to understand your specific situation, your doctors, medications, budget, and healthcare patterns. At Your Medicare Advantage Guy, we provide exactly that kind of personalized guidance at no cost and with no obligation. We compare plans from multiple top-rated carriers and help you keep your preferred doctors in-network while finding coverage that fits your budget. Get started today with a free consultation and discover how much you might save on your Medicare Advantage plan.
Frequently Asked Questions
What are the Medicare Advantage enrollment deadlines for 2026?
The Annual Enrollment Period (AEP) runs from October 15 to December 7 each year, during which you can enroll in or switch Medicare Advantage plans. If you're turning 65, your Initial Enrollment Period gives you three months before and after your birthday month to enroll. Missing these deadlines means waiting until the next AEP unless you qualify for a Special Enrollment Period due to a qualifying life event.
How do I know if an independent Medicare insurance agent is actually independent?
A truly independent Medicare insurance agent can present plans from multiple carriers, not just one or two. Ask directly: 'Which carriers can you show me plans from?' Verify they hold an active, current license through your state's insurance department. Independent agents should explain how they're compensated and confirm they receive the same commission regardless of which plan you choose. Your Medicare Advantage Guy is licensed and compares options from top-rated carriers with no obligation to you.
Can I switch Medicare Advantage plans outside the Annual Enrollment Period?
You can switch plans during the Annual Enrollment Period (October 15-December 7) or if you qualify for a Special Enrollment Period. Qualifying events include moving out of your plan's service area, losing employer coverage, becoming eligible for Medicaid, or experiencing certain life changes. Some dual-eligible individuals have additional opportunities to switch. Contact Medicare or a licensed agent to confirm whether your situation qualifies for a Special Enrollment Period.
What should I check before enrolling in a Medicare Advantage plan to avoid coverage surprises?
Verify your current doctors and pharmacies are in the plan's network by checking the plan's provider directory directly with each provider's office, don't rely solely on online searches. Confirm prescription drug coverage for all your medications, including whether they require prior authorization. Review the deductible, copayments, and out-of-pocket maximums. Check Star Ratings for quality and member satisfaction. Use a pre-enrollment checklist to document this information before making your final choice.
This article was written using GrandRanker